

Sorry, we are not able to source the book you are looking for right now.
We did a search for other books with a similar title, however there were no matches. You can try selecting from a similar category, click on the author's name, or use the search box above to find your book.
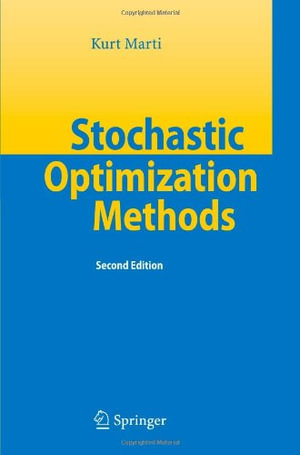
ISBN: 9783642098369
ISBN-10: 3642098363
Published: 6th November 2010
Format: Paperback
Language: English
Number of Pages: 356
Audience: General Adult
Publisher: Springer Nature B.V.
Country of Publication: DE
Edition Number: 2
Edition Type: Revised
Dimensions (cm): 23.39 x 15.6 x 1.88
Weight (kg): 0.5
Shipping
| Standard Shipping | Express Shipping | |
|---|---|---|
| Metro postcodes: | $9.99 | $14.95 |
| Regional postcodes: | $9.99 | $14.95 |
| Rural postcodes: | $9.99 | $14.95 |
Orders over $0.00 qualify for free shipping.
How to return your order
At Booktopia, we offer hassle-free returns in accordance with our returns policy. If you wish to return an item, please get in touch with Booktopia Customer Care.
Additional postage charges may be applicable.
Defective items
If there is a problem with any of the items received for your order then the Booktopia Customer Care team is ready to assist you.
For more info please visit our Help Centre.
You Can Find This Book In

RRP $65.95
$49.75
OFF

RRP $46.95
$36.75
OFF

RRP $49.95
$38.75
OFF

RRP $49.95
$38.75
OFF

RRP $152.00
$121.60
OFF
RRP $49.95
$49.75


RRP $178.00
$176.75


RRP $192.95
$143.75
OFF

RRP $141.00
$117.75
OFF


RRP $126.95
$100.75
OFF

$595.75


This product is categorised by
- Non-FictionMathematicsApplied MathematicsStochastics
- Non-FictionBusiness & ManagementOperational Research
- Non-FictionMathematicsOptimisationLinear Programming
- Non-FictionEngineering & TechnologyTechnology in GeneralEngineering in General
- Non-FictionBusiness & ManagementBusiness Mathematics & Systems
- Non-FictionComputing & I.T.Computer ScienceArtificial Intelligence
- Non-FictionMathematicsProbability & Statistics
- Non-FictionEconomics
- Non-FictionBusiness & ManagementManagement & Management TechniquesManagement Decision Making