
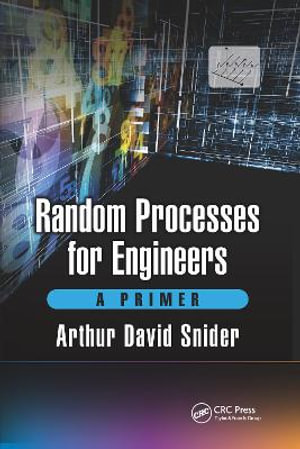
Random Processes for Engineers
A Primer
Paperback | 30 September 2020 | Edition Number 1
At a Glance
Paperback
RRP $126.00
$114.75
Ships in 3 to 5 business days
ISBN: 9780367656355
ISBN-10: 0367656353
Published: 30th September 2020
Format: Paperback
Language: English
Number of Pages: 208
Audience: General Adult
Publisher: Taylor & Francis Ltd
Country of Publication: GB
Edition Number: 1
Dimensions (cm): 23.39 x 15.6 x 1.12
Weight (kg): 0.3
Shipping
| Standard Shipping | Express Shipping | |
|---|---|---|
| Metro postcodes: | $9.99 | $14.95 |
| Regional postcodes: | $9.99 | $14.95 |
| Rural postcodes: | $9.99 | $14.95 |
How to return your order
At Booktopia, we offer hassle-free returns in accordance with our returns policy. If you wish to return an item, please get in touch with Booktopia Customer Care.
Additional postage charges may be applicable.
Defective items
If there is a problem with any of the items received for your order then the Booktopia Customer Care team is ready to assist you.
For more info please visit our Help Centre.
You Can Find This Book In

RRP $273.00
$236.99
OFF





RRP $70.00
$52.75
OFF
RRP $119.96
$113.75

RRP $166.90
$132.75
OFF

RRP $38.00
$30.40
OFF

RRP $128.99
$101.75
OFF

RRP $117.99
$89.75
OFF
RRP $129.95
$121.99


RRP $307.00
$255.75
OFF

RRP $117.99
$93.75
OFF

RRP $204.95
$155.75
OFF
RRP $170.95
$117.75
OFF

RRP $283.95
$184.75
OFF
This product is categorised by
- Non-FictionEngineering & TechnologyElectronics & Communications EngineeringCommunications Engineering & Telecommunications
- Non-FictionEngineering & TechnologyTransport Technology & TradesAutomotive Technology & Trades
- Non-FictionEngineering & TechnologyEnergy Technology & EngineeringElectrical EngineeringPower Generation & Distribution
- Non-FictionMathematicsProbability & Statistics
- Non-FictionEngineering & TechnologyMechanical Engineering & MaterialsMechanical Engineering
- Non-FictionEngineering & TechnologyEnvironmental Science
- Non-FictionMathematicsApplied MathematicsStochastics